Construction Insurance
Construction Insurance Quotes
Cover for sites, tools and the people on them.

Partnered with Quotezone
We’re partnered with Quotezone. As an Introducer Appointed Representative of Seopa Ltd (FCA FRN: 313860), we receive a commission if you purchase insurance products via SimplyQuote.co.uk.
We do not provide advice or make recommendations. Your choice of provider is entirely your own.




Compare insurance quotes from UK’s leading construction site insurers including:
What Is Construction Insurance?
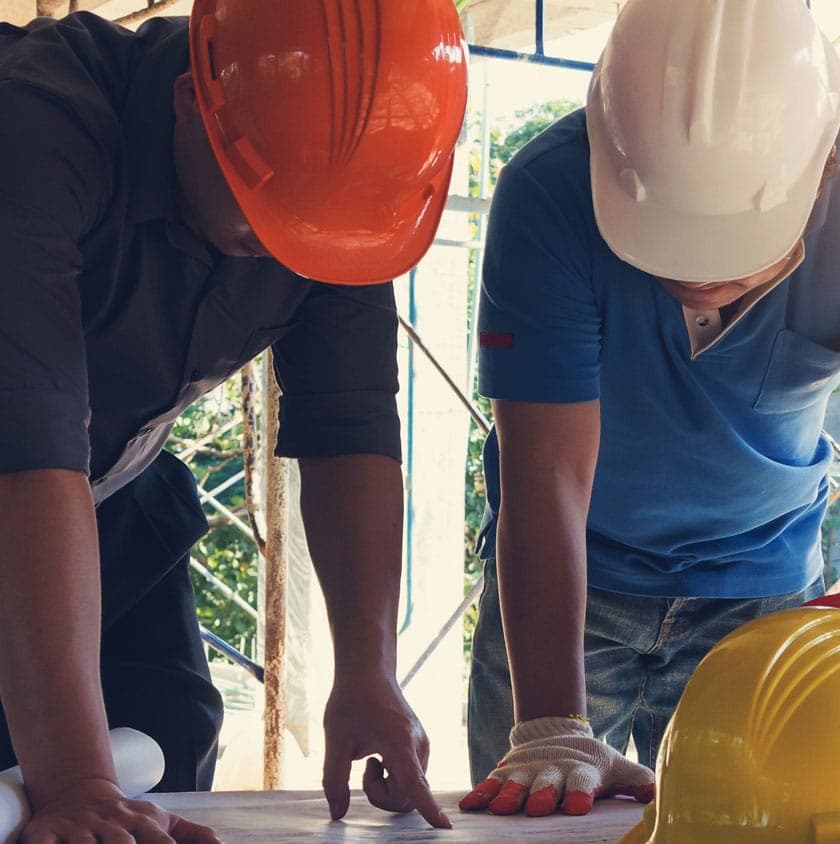
Construction insurance is a package of cover designed to protect builders, contractors, and construction businesses against the financial risks of working on site.
It typically bundles public liability insurance with employers’ liability, tool cover, and contract works protection into a single policy. The exact combination depends on the size of your operation and the type of work you carry out.
Construction is one of the highest-risk industries in the UK, and the tradesman insurance market reflects that. A single accident on site can lead to injury claims, property damage, and project delays that cost far more than the premium you would have paid for cover.
How To Compare Construction Insurance Quotes
Comparing construction insurance quotes takes a few minutes when you use an online comparison tool that specialises in trade policies.
Enter your trade and business details
Select construction as your trade, then provide your postcode, annual turnover, number of employees, and whether you use subcontractors.
Choose your cover levels
Pick your public liability limit and add any extras you need, such as employers’ liability, tool cover, or contract works insurance.
Compare quotes side by side
Review each quote on price, cover limits, and exclusions. Confirm that every insurer on the panel is regulated by the Financial Conduct Authority before you buy.
Buy your policy online
Complete the purchase and download your certificate of insurance straight away so you can show it on site the same day.
What Does Construction Insurance Cover?
A standard construction insurance policy bundles several types of cover into one package tailored to the risks of working on site.
Public Liability Insurance
Public liability covers compensation and legal costs if a member of the public is injured or their property is damaged because of your work. Cover levels typically range from £1 million to £10 million.
Most main contractors and site managers require at least £5 million before they let you start work.
Employers’ Liability Insurance
If you employ anyone, including casual labourers and labour-only subcontractors, employers’ liability insurance is a legal requirement under the Employers’ Liability (Compulsory Insurance) Act 1969. The legal minimum is £5 million, though most insurers provide £10 million as standard.
Contract Works Insurance
Contract works cover (also called contractors’ all risks) protects the value of work in progress if it is damaged by fire, flood, storm, theft, or vandalism before handover. It covers materials, labour costs, and temporary works.
Tool and Equipment Cover
Tool cover replaces or repairs your tools and equipment if they are stolen, lost, or damaged. Policies usually cover items in your van, on site, and in storage up to an agreed limit.
Personal Accident Cover
Personal accident insurance pays a lump sum or weekly benefit if you are injured and cannot work. For sole traders without sick pay, this can keep the business running while you recover.
Who Needs Construction Insurance?
Anyone who works on a construction site or manages construction projects should carry construction insurance.
| Who | Why They Need Cover |
| Self-employed builders | Public liability protects against injury and damage claims |
| Main contractors | Required to show proof of cover to win contracts |
| Subcontractors | Site managers demand insurance before you start work |
| Roofing and scaffolding firms | Working at height carries higher risk and higher claims |
| Groundworkers and plant operators | Excavation and heavy machinery increase liability exposure |
| Construction project managers | Professional indemnity covers advice and design errors |
Is Construction Insurance A Legal Requirement?
Public liability insurance is not a legal requirement, but most clients and site managers will not let you start without it. Employers’ liability is legally required if you hire staff, with fines of up to £2,500 per day for non-compliance.
Compare Construction Insurance
Compare construction insurance quotes from UK insurers in minutes.
What Is Not Covered By Construction Insurance?
Standard policies exclude several scenarios that can catch contractors off guard if they do not read the policy wording.
Poor Workmanship
Insurance covers accidental damage and third-party claims, not the cost of redoing work that was done badly. If a client complains about the quality of your build, that is a contract dispute, not an insurable event.
Work Outside Your Declared Trade
If your policy covers general building but you take on roofing, demolition, or asbestos removal without updating it, your insurer can decline the claim.
Unsecured Tools and Equipment
Leaving tools in an unlocked van or on an open site overnight can void your tool cover. Most insurers require lockable storage or a secured vehicle.
Deliberate Non-compliance with Safety Regulations
Ignoring Health and Safety Executive regulations, working without required training, or failing to carry out risk assessments can invalidate your policy.
Wear and Tear on Equipment
Gradual deterioration of tools and machinery is a maintenance issue, not an insurable loss. Keep your equipment serviced and replace worn items before they fail.
What Add-Ons Are Available For Construction Insurance?
Most insurers let you add extra cover to your base policy to close gaps specific to your type of work.
Professional Indemnity Insurance
Professional indemnity insurance covers you if a client claims your advice, design work, or project management caused them a financial loss. It is increasingly required on contracts that involve design-and-build elements.
Commercial Vehicle Insurance
If you use a van or pickup to transport tools and materials between sites, van insurance with goods-in-transit cover protects your load on the road.
Legal Expenses Cover
Pays solicitor and court costs if you need to pursue an unpaid invoice, defend an employment tribunal, or challenge a contract dispute.
Business Interruption Insurance
Compensates you for lost income if your business has to stop trading temporarily after a covered event such as a fire at your storage unit or a flood on site.
How Much Does Construction Insurance Cost?
Construction insurance for a self-employed builder starts from around £70 to £200 per year for public liability only. Adding employers’ liability, tool cover, and contract works pushes the cost higher.
| Cover Type | Sole Trader | Small Firm (2–5 staff) | Mid-Size Contractor (6–15 staff) |
| £1m public liability | £70–£200 | £200–£400 | £400–£700 |
| £5m public liability | £120–£350 | £350–£600 | £600–£1,100 |
| £10m public liability | £180–£500 | £500–£900 | £900–£1,600 |
| Add EL (£10m) | +£80–£160 | +£160–£350 | +£350–£600 |
| Tool cover (£5k–£15k) | +£50–£120 | +£100–£250 | +£200–£400 |
Paying monthly instead of annually typically adds 8–11% to the total cost over the year.
A self-employed bricklayer in Manchester with £5 million public liability, £7,500 of tool cover, and no employees might pay £150–£400 per year. Adding one labourer with £10 million employers’ liability could bring the total to £350–£650.
What Affects Your Construction Insurance Premium?
Insurers price construction policies based on the level of risk your work presents and the amount of cover you need.
Type of Construction Work
High-risk trades like scaffolding, roofing, and demolition attract higher premiums than lower-risk work such as plastering or painting.
Working at Height
Any work above ground level increases the premium. The higher you work and the more frequently you do it, the more you pay.
Number of Employees and Subcontractors
More workers on site means more potential claims. Each additional employee or subcontractor adds to your employers’ liability cost.
Annual Turnover
Turnover is used as a proxy for the scale of your operation. A £500,000 turnover attracts a higher premium than a £50,000 sole trader business.
Claims History
A clean claims record keeps your premium low. One or two claims in the past three to five years can increase the cost by 20–40%.
Location
Urban areas with higher footfall and theft rates tend to carry higher premiums than rural locations.
How To Save Money On Construction Insurance
There are several ways to reduce your premium without cutting the cover you actually need.
Compare Quotes from Multiple Insurers
Prices vary widely between providers. Using a business insurance comparison tool lets you see quotes side by side in minutes.
Match Your Cover to Your Actual Work
If you are a general builder doing domestic extensions, you probably do not need £10 million public liability. Choose the level your contracts require and no more.
Pay Annually Instead of Monthly
Monthly instalments spread the cost but add 8–11% in interest over the year. Paying upfront saves you that markup.
Invest in Site Security
CCTV, alarm systems, lockable tool storage, and fenced perimeters reduce theft risk and can earn you a discount from your insurer.
Keep a Clean Claims Record
Paying out of pocket for minor incidents protects your no-claims history and keeps your long-term premium lower.
Hold Recognised Qualifications
A Construction Industry Training Board health and safety test, a CSCS card, or an NVQ in your trade shows insurers you take safety seriously. Some providers offer a discount for qualified tradespeople.
Compare Construction Insurance
Compare construction insurance quotes from UK insurers in minutes.

Frequently Asked Questions
Public liability insurance is not legally required, but most clients and site managers will not let you work without it. Employers’ liability is a legal requirement if you hire staff, with fines of up to £2,500 per day for non-compliance.
They cover the same core risks. Construction insurance is a broader term that includes all site-based trades, while builders insurance is often marketed specifically at general builders and bricklayers.
Most main contractors require subcontractors to hold their own public liability insurance before they can start on site. Relying on the main contractor’s policy usually does not cover you.
Tool cover is usually an optional add-on, not included in the base policy. You choose a cover limit based on the total replacement value of your tools and equipment.
Yes, but you must declare it when you apply. Working at height increases your premium because it carries a higher risk of injury claims.
Contract works insurance (also called contractors’ all risks) covers the value of work in progress if it is damaged by fire, flood, storm, theft, or vandalism before you hand it over to the client.
Short-term policies are available for individual projects or fixed periods, from one day to three months. They are useful if you only take on occasional contract work.
One or two claims in the past three to five years can increase your premium by 20–40%. A clean claims record keeps your costs lower over time.
You need it if your work involves design, project management, or giving technical advice. Clients on design-and-build contracts increasingly require it as standard.
Yes. Most insurers offer monthly payment plans, but they typically add 8–11% in interest over the year compared to paying the full premium upfront.
Public Liability Insurance Guides