Static Caravan Insurance
Static Caravan Insurance Quotes
Protect your static caravan against damage, theft & unexpected risks.
Partnered with Quotezone
We’re partnered with Quotezone. As an Introducer Appointed Representative of Seopa Ltd (FCA FRN: 313860), we receive a commission if you purchase insurance products via SimplyQuote.co.uk.
We do not provide advice or make recommendations. Your choice of provider is entirely your own.




Compare quotes from up to 50 UK static caravan insurers, including;
What Is Static Caravan Insurance?
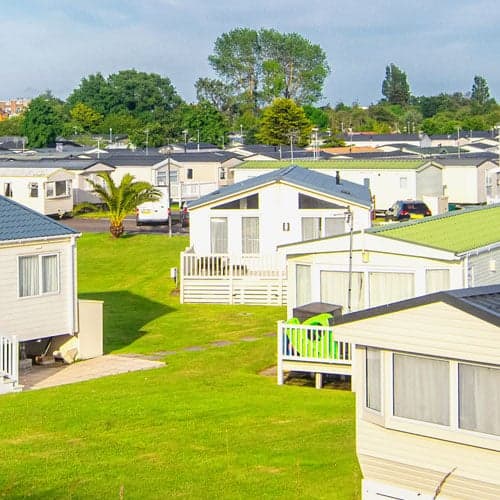
Static caravan insurance is a specialist policy that protects your holiday home against theft, storm damage, fire, and accidental damage while it sits on its pitch.
A standard home insurance policy does not cover a static caravan, even if you own it outright. Static caravans face different risks to bricks-and-mortar properties, including exposure to high winds, flooding, and long periods left unoccupied.
With hundreds of thousands of static caravan holiday homes across the UK, specialist cover is widely available from providers that understand these risks. Most holiday parks also require proof of insurance as a condition of your site agreement.
How To Compare Static Caravan Insurance Quotes
Comparing static caravan insurance quotes online takes a few minutes and can save you over £100 a year.
Enter Your Caravan Details
Provide the make, model, year of manufacture, dimensions, and the current value of your static caravan. Include the site name and postcode where it is pitched.
Choose Your Cover Level
Decide between new-for-old replacement or market value cover, and select whether you want comprehensive protection or third-party only. New-for-old costs more but replaces your caravan with a brand-new model.
Add Any Extras You Need
Review optional add-ons such as contents cover, legal expenses, and emergency accommodation. Pick only the extras that match how you use your caravan.
Compare and Buy
Review the quotes side by side, checking excesses and exclusions as well as the headline price. Confirm the insurer is listed on the FCA Register before you buy.
What Does Static Caravan Insurance Cover?
A comprehensive static caravan insurance policy covers a wide range of risks, from storm damage and theft to public liability claims.
Storm and Weather Damage
High winds, heavy rain, flooding, and snow can all cause serious damage to a static caravan. According to the Association of British Insurers, weather-related incidents account for around a third of all holiday caravan insurance claims.
Theft and Vandalism
Cover pays out if your caravan or its contents are stolen, or if the caravan is damaged by vandals. Security measures such as alarms and CCTV on the site can help reduce your premium.
Fire Damage
Fire cover protects against damage caused by accidental fires, electrical faults, or arson. This extends to the structure and any fixed fittings inside the caravan.
Accidental Damage
Accidental damage cover pays for repairs if something unexpected happens, such as a window being broken or a pipe bursting inside the caravan during cold weather.
Public Liability
Most policies include between £2 million and £5 million of public liability cover. This protects you if a visitor is injured or their property is damaged while at your caravan.
Site Clearance
If your caravan is destroyed, site clearance cover pays the cost of removing debris from the pitch. Without it, you would need to cover this yourself before a replacement can be sited.
Compare Static Caravan Insurance
Compare static caravan insurance quotes from UK insurers in minutes.
What Types Of Static Caravan Insurance Can You Get?
Static caravan insurance policies differ in two ways: the cover level and how your caravan is valued if it needs to be replaced.
| Policy Type | What It Means | Best For |
| New-for-Old (Comprehensive) | Replaces your caravan with a brand-new model of the same make and spec if it is written off or stolen | Newer caravans under 15 years old |
| Market Value (Comprehensive) | Pays out the current market value of your caravan at the time of the claim, factoring in depreciation | Older caravans or those on a tighter budget |
| Third-Party Only | Covers damage you cause to other people or their property but does not protect your own caravan | Rarely used for static caravans |
New-for-old is the most popular choice for caravans under 10 to 15 years old. If you own a touring caravan as well, check whether your provider offers a multi-caravan discount.
What Is Not Covered By Static Caravan Insurance?
Every policy has exclusions, and knowing what is not covered helps you avoid gaps when you need to claim.
Wear and Tear
Gradual deterioration, rust, and ageing are maintenance issues, not insurable events. Insurers expect you to keep the caravan in a reasonable condition.
Poor Maintenance
Damage caused by neglect, such as a leaking roof you knew about but did not repair, is typically excluded. Regular servicing protects both the caravan and your cover.
Damage During Transit
If your static caravan is moved to a new site and damaged in transit, standard policies will not cover it. You would need a separate transit or re-siting policy for the move.
Pest Damage
Damage from rodents, insects, or other pests is usually excluded. Some insurers offer vermin cover as a paid add-on if your site is in a rural area.
Unoccupied Period Restrictions
Some policies limit cover if the caravan is left empty for more than a set number of consecutive days, typically 30 to 60. Check your policy if your caravan sits unused over winter.
How Does A Static Caravan Insurance Claim Work?
Filing a claim on your static caravan insurance follows a similar process to a home insurance claim, with a few extra steps for site-based properties.
Step-by-Step Process
Contact your insurer as soon as you discover the damage. Provide photographs, a written description, and a crime reference number if theft or vandalism is involved.
An assessor will visit the site to inspect the caravan. For weather damage claims, the insurer may request a report from the site manager confirming the conditions at the time.
A winter storm tears off part of the roof and water damages the interior flooring and furniture. The total repair bill comes to £4,500.
Your comprehensive policy has a £150 excess. The insurer pays £4,350 directly to the approved repairer, and the work is completed within six weeks before the new season starts.
How Much Does Static Caravan Insurance Cost?
Static caravan insurance typically costs between £150 and £500 a year, depending on the caravan's value, its location, and the cover level you choose.
| Caravan Value | Typical Annual Premium | Key Factor |
| Under £20,000 | £150–£250 | Lower replacement cost |
| £20,000–£40,000 | £250–£400 | Standard holiday home range |
| £40,000–£80,000 | £350–£500 | Higher-spec models |
| Over £80,000 | £450–£600+ | Lodge-style or luxury units |
Caravans on sites in flood-prone or coastal areas will sit at the higher end of these ranges. A clean claims history and good site security can bring the cost down.
What Affects Your Premium?
The main factors are your caravan's age, value, and location. Whether you rent it out, how many months of the year it is occupied, and the security features on site all play a role.
You can check whether your site is in a flood risk area using the GOV.UK flood risk service. Sites with a history of flooding may attract higher premiums or specific policy conditions.
How To Save Money On Static Caravan Insurance
A few practical steps can reduce your static caravan insurance premium without cutting the cover you need.
Improve Site Security
Alarms, wheel clamps on neighbouring units, CCTV, and gated access all reduce the theft risk. Insurers reward sites with strong security by lowering premiums.
Increase Your Voluntary Excess
Raising the excess from £100 to £250 can bring the annual premium down. Only choose an excess you could comfortably pay if you needed to claim.
Maintain a No-Claims Record
A clean claims history over several years builds a no-claims discount that compounds over time. Small repairs may be cheaper to cover yourself than to claim for.
Choose Market Value If Your Caravan Is Older
Switching from new-for-old to market value cover reduces the premium on caravans that have already depreciated. This makes sense for units over 15 years old.
Compare Quotes Every Year
Premiums vary between providers, and loyalty rarely pays. Comparing quotes at renewal takes minutes and can save you £100 or more.
Compare Static Caravan Insurance
Compare static caravan insurance quotes from UK insurers in minutes.
What Add-Ons Can You Get For Static Caravan Insurance?
Most static caravan insurers offer optional extras that let you tailor your policy to how you use your caravan.
Contents Cover
Protects personal belongings inside the caravan, from electronics to furniture, with limits typically ranging from £3,000 to £10,000.
Loss of Rent Cover
If you rent out your caravan and an insured event makes it uninhabitable, this add-on covers the lost rental income. Owners who let their caravans may also want to review landlord building insurance for comparison.
Emergency Accommodation
Pays for alternative accommodation if your caravan is damaged and you cannot stay in it during a planned visit. This is useful if you use the caravan as your main holiday base.
Legal Expenses Cover
Covers solicitor fees and court costs if you face a legal dispute related to your caravan, such as a disagreement with the site owner or a personal injury claim.
Vermin Cover
Pest damage is excluded from most standard policies. This add-on covers repairs caused by rodents or insects, which is worth considering if your site is in a rural or coastal location.
If you need higher cover, a standalone contents insurance policy may offer better value.
If you also own a motorhome or campervan, some providers offer multi-vehicle discounts when you bundle your motorhome insurance with your static caravan cover.

Frequently Asked Questions
No, it is not a legal requirement in the UK. However, most holiday parks require proof of insurance as a condition of your pitch agreement, so you may not be able to keep your caravan on site without it.
No, a standard home insurance policy does not cover a static caravan. You need a dedicated static caravan insurance policy to protect it.
Yes, but you need to tell your insurer that you let the caravan to paying guests. Most providers offer a hiring-out extension or a specific letting policy.
Some policies include basic contents cover as standard, while others offer it as a paid add-on. Check the limit and make sure it matches the value of what you keep inside.
Yes, many insurers set a maximum age, typically between 15 and 25 years from the date of manufacture. Older caravans may still be insurable through specialist providers.
Comprehensive policies cover storm, flood, and weather damage as standard. If your site is in a flood-prone area, check whether your policy has any specific flood exclusions or higher excesses.
New-for-old cover replaces your caravan with a brand-new model of the same make and specification if it is written off or stolen. It costs more than market value cover but gives better protection for newer caravans.
Yes, most insurers offer monthly payment plans. Paying monthly usually costs slightly more than paying annually because of interest charges.
If your site closes or your pitch agreement ends, contact your insurer immediately. Cover may be affected if the caravan needs to be moved or is left without site security.
Yes, winter is when your caravan faces the highest risk from storms, flooding, and theft. Cancelling cover for the off-season leaves you exposed to the most costly claims.
For more options across the caravan insurance range, including touring and static cover, compare quotes from trusted UK providers.
Policies are not usually transferable. If you sell your caravan, cancel your policy and the new owner will need to arrange their own cover.
Yes, comprehensive policies cover accidental damage to both the structure and fixed internal fittings. Check whether the policy also covers accidental damage to contents.