Non-Standard Home Insurance
Insurance Quotes for Non-Standard Homes
Find specialist home insurance for non-standard properties.

Partnered with Quotezone
We’re partnered with Quotezone. As an Introducer Appointed Representative of Seopa Ltd (FCA FRN: 313860), we receive a commission if you purchase insurance products via SimplyQuote.co.uk.
We do not provide advice or make recommendations. Your choice of provider is entirely your own.




Policies and deals from leading insurance providers, including
What Is Non-Standard Home Insurance?
Non-standard home insurance is a specialist policy designed for properties built with materials or methods that fall outside the conventional brick walls and slate or tile roof construction.
Standard home insurance assumes your property is built from brick or stone with a tile or slate roof. If your home uses timber frames, thatched roofing, prefabricated concrete, steel frames, or flat roofing materials, most standard policies will either exclude it or charge a heavy premium.
Non-standard construction also includes listed buildings, properties in flood-risk areas, and homes with unusual features such as underpinning or a history of subsidence.
How To Compare Non-Standard Home Insurance
Comparing quotes from specialist insurers is the fastest way to find cover that reflects your property type and construction materials.
Describe your property
Provide the construction materials for the walls and roof, the year the property was built, and any listing status or flood history.
Enter the rebuild cost
Your rebuild cost is the amount it would take to reconstruct the property from scratch, not its market value. A chartered surveyor can provide an accurate figure.
Choose your cover level
Select buildings only, contents only, or a combined policy. Read more about what home insurance covers to decide which level suits you.
Compare quotes and buy online
Review offers from specialist insurers side by side. The FCA regulates all UK insurance providers, so every quote you receive meets the same consumer protection standards.
What Does Non-Standard Home Insurance Cover?
Non-standard home insurance covers the same core risks as a standard policy, with additional protection tailored to the specific vulnerabilities of your property type.
Buildings insurance
This covers the structure of your home, including walls, roof, floors, and permanent fixtures such as fitted kitchens and bathrooms. For non-standard properties, buildings cover accounts for the higher cost of specialist materials and labour.
Contents insurance
Contents insurance protects your personal belongings, furniture, and valuables inside the property. The construction type does not usually affect contents cover, but the location and security of the building can.
Subsidence and ground movement
If the ground beneath your property shifts, causing cracks or structural damage, this cover pays for investigation and repairs. Properties with a history of subsidence may face higher excesses.
Fire damage
Thatched and timber-framed homes carry a higher fire risk than brick-built properties. Non-standard policies reflect this with cover limits and conditions specific to your construction type.
Flood damage
Properties in flood-risk areas need policies that explicitly include flood cover. You can check whether your property is at risk using the government flood checker before applying for quotes.
Theft and vandalism
Break-ins, attempted theft, and malicious damage to the property are covered. Insurers may require specific security measures such as approved locks and alarm systems.
Compare Non-Standard Home Insurance
Compare non-standard home insurance quotes from UK insurers in minutes.
What Is Not Covered By Non-Standard Home Insurance?
Every policy has exclusions, and understanding them helps you avoid unexpected gaps in your cover.
General wear and tear
Gradual deterioration such as rotting timber, crumbling mortar, or ageing thatch is a maintenance issue. Insurers expect you to keep the property in good repair.
Known unfixed problems
If you are aware of a structural issue and have not taken steps to fix it, any resulting damage is unlikely to be covered. Documented maintenance records strengthen future claims.
Poor workmanship
Damage caused by substandard building work or incorrect use of materials is excluded. Always use qualified tradespeople who are experienced with your property type.
Design faults
If the original construction design is flawed and leads to structural failure, this falls outside the scope of most policies. A structural survey can identify design weaknesses before they cause problems.
Contractor liability
Damage caused by contractors working on your property is their responsibility, not your insurer's. Check that any contractor carries their own public liability insurance.
Cosmetic damage
Scratches, dents, and surface marks that do not affect the structural integrity of the property are not covered. This includes minor plaster cracking from normal settlement.
Who Needs Non-Standard Home Insurance?
Any homeowner whose property does not meet the standard definition of brick walls with a tile or slate roof should check whether specialist cover is needed.
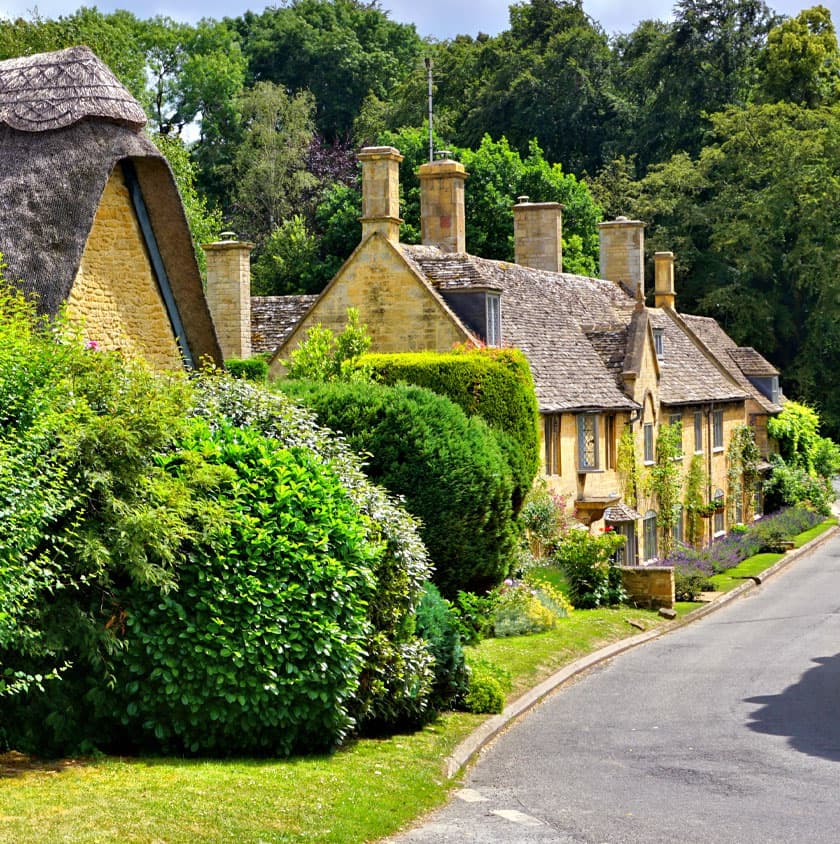
Thatched roof homes
Thatched properties carry a higher fire risk and need regular maintenance. Insurers may require proof of fire-retardant spray treatment as a condition of cover.
Listed buildings
Grade I, Grade II, and Grade II* listed buildings must be repaired using historically appropriate materials and methods. You can check your property's listing status on the Historic England register.
Timber-framed properties
Timber frames are common in older homes and some modern eco-builds. The fire risk and potential for rot or pest damage make these properties non-standard in most insurers' assessments.
Flat or non-tile roofs
Properties with flat, rubber, felt, or corrugated metal roofs fall outside standard construction definitions. Flat roofs can be more prone to leaks and water pooling.
Prefabricated concrete homes
Post-war prefab homes built from reinforced concrete panels, including BISF, Airey, and Cornish Unit types, are classified as non-standard. Some of these have been reclassified after repair under PRC certificate schemes.
Properties in flood-risk areas
Even a conventionally built home may need non-standard cover if it sits in a high-risk flood zone. Flood Re, a joint scheme between insurers and the government, helps keep premiums affordable.
| Construction Type | Key Risk | Typical Premium Impact |
| Thatched roof | Fire, maintenance costs | Highest (+300–500%) |
| Listed building | Repair material costs | High (+30–150%) |
| Timber frame | Fire, rot, pests | Moderate (+10–30%) |
| Flat roof | Leaks, water pooling | Moderate (+20–50%) |
| Prefab concrete | Structural concerns | Moderate (+20–60%) |
| Flood-risk area | Flood damage | Variable (Flood Re may apply) |
How Much Does Non-Standard Home Insurance Cost?
Non-standard home insurance typically costs between £300 and £3,000+ per year, depending on the construction type, location, and rebuild cost of the property.
| Property Type | Typical Annual Premium |
| Timber frame | £300–£500 |
| Flat roof | £350–£550 |
| Prefab concrete | £350–£600 |
| Listed building | £500–£1,200 |
| Thatched roof | £1,500–£3,000+ |
| Flood-risk area | £400–£800 |
What affects your premium?
Insurers price non-standard policies based on the construction materials, rebuild cost, location, property age, security features, and claims history. The ABI notes that specialist materials and labour shortages can push rebuild costs well above those of standard homes.
Why are thatched properties the most expensive to insure?
Thatched roofs need re-ridging every 10–15 years and full re-thatching every 20–40 years, depending on the material. The fire risk is higher, and the cost of specialist thatch work drives up both the rebuild value and the premium.
What Add-Ons Are Available For Non-Standard Home Insurance?
Most specialist insurers offer optional extras that let you tailor your policy to your property's specific needs.
Accidental damage
This covers unintentional damage to the building or contents, such as putting a foot through a ceiling or spilling paint on a period floor.
Legal expenses
This pays for legal costs arising from property disputes, boundary issues, or personal injury claims connected to the property.
Home emergency cover
Provides 24/7 access to emergency tradespeople for burst pipes, boiler breakdowns, or broken locks. This is especially valuable for older properties prone to unexpected failures.
Personal belongings away from home
Standard contents cover only protects items inside the property. This add-on extends cover to belongings you carry with you, such as laptops, phones, and jewellery.
Outbuildings cover
If your property includes outbuildings constructed from non-standard materials, such as a timber barn or a thatched garage, this extension brings them under the same policy.
Alternative accommodation
If your home becomes uninhabitable due to an insured event, this pays for temporary housing while repairs are completed. Repairs to non-standard homes often take longer than standard builds.
How To Save Money On Non-Standard Home Insurance
Non-standard premiums are higher than average, but several practical steps can bring the cost down without reducing your cover.
Compare quotes from specialist insurers
Mainstream insurers often decline non-standard properties or quote high prices. Using a home insurance comparison tool that includes specialist providers gives you access to competitive rates you would not find on the high street.
Improve security
Fitting approved locks, a monitored burglar alarm, and external lighting can reduce your premium. Some insurers offer discounts of 5–15% for upgraded security.
Maintain the property regularly
A well-maintained non-standard home is a lower risk. Keep records of roof inspections, timber treatments, and damp-proofing work to show your insurer.
Pay annually instead of monthly
Monthly payments usually include interest that adds 8–10% to the total cost. Paying the full premium upfront is almost always cheaper.
Increase your voluntary excess
Agreeing to pay a higher amount towards any claim reduces your premium. Set the excess at a level you could comfortably afford if you needed to claim.
Build a no-claims discount
Each claim-free year adds to your no-claims bonus, which can reduce your renewal premium by up to 50% over five years. Protect it with a no-claims discount guarantee if available.
Remove unnecessary add-ons
If the property is a buy-to-let or unoccupied, you may not need personal belongings cover or home emergency assistance. Only pay for add-ons that match your actual situation.
Compare Non-Standard Home Insurance
Compare non-standard home insurance quotes from UK insurers in minutes.

Frequently Asked Questions
Non-standard home insurance covers properties built with materials or methods outside the conventional brick walls and tile or slate roof. It also covers listed buildings, homes in flood-risk areas, and properties with a history of subsidence.
Non-standard materials include timber frames, thatched roofs, prefabricated concrete panels, steel frames, flat roofs made from felt or rubber, corrugated metal, and cob or wattle-and-daub walls.
Check your property deeds or the original building survey for details of the construction materials. If your walls are not brick or stone, or your roof is not tile or slate, your home is likely classed as non-standard.
Yes, premiums are typically 20–500% higher than standard home insurance because the materials cost more to repair or replace and the risks are often greater.
Yes, but some lenders are cautious about certain construction types. A PRC certificate, which confirms structural repairs have been completed, can make prefab homes more mortgageable.
If you own the property, buildings insurance is almost always required by your mortgage lender. Contents cover is optional but protects your personal belongings inside the home.
Some non-standard policies include landlord-specific cover, but a dedicated landlord insurance policy is usually a better fit if you are letting the property to tenants.
A PRC (Prefabricated Reinforced Concrete) certificate confirms that a prefab home has undergone approved structural repairs. It can improve mortgageability and may reduce insurance premiums.
Many eco-homes use timber frames, straw bales, or other unconventional materials, which puts them in the non-standard category. Passive houses and zero-emission buildings often need specialist cover too.
Yes, converting a non-standard feature, such as replacing a flat roof with a pitched tile roof, can bring your property closer to standard classification and reduce your premium.
No, there is no UK law requiring any type of home insurance. However, your mortgage lender will almost certainly require buildings insurance as a condition of the loan.