Fleet Insurance
Compare Fleet Insurance Quotes
Find fleet insurance that covers multiple vehicles under one policy.
Partnered with Quotezone
We’re partnered with Quotezone. As an Introducer Appointed Representative of Seopa Ltd (FCA FRN: 313860), we receive a commission if you purchase insurance products via SimplyQuote.co.uk.
We do not provide advice or make recommendations. Your choice of provider is entirely your own.





Compare fleet insurance policies from leading insurers, including;
What Is Fleet Insurance?
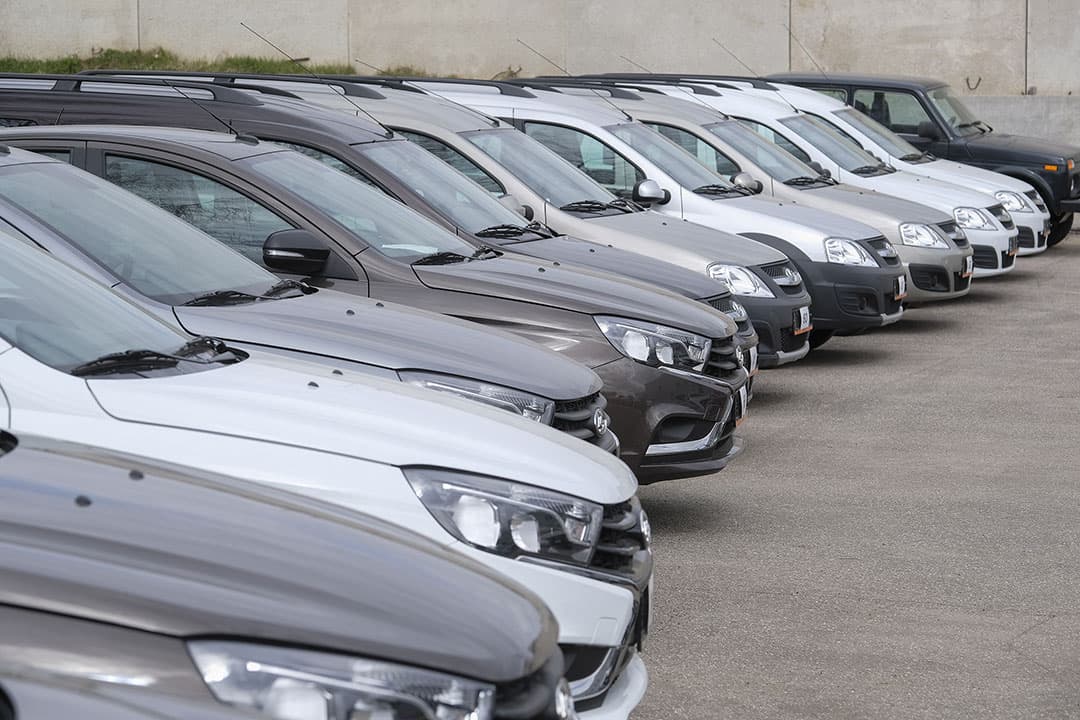
Fleet insurance is a single policy that covers two or more vehicles under one agreement, giving businesses and families a cheaper and simpler alternative to insuring each vehicle individually.
Most fleet insurers accept fleets from 2 to 100+ vehicles, including cars, vans, HGVs, minibuses, and specialist vehicles. One renewal date, one set of terms, and one point of contact replace the admin burden of managing multiple individual policies.
Fleet policies are most common among businesses that rely on vehicles for deliveries, client visits, or transport. Family fleets of two or more cars at the same address also qualify.
How To Compare Fleet Insurance
Comparing fleet insurance quotes from specialist providers is the quickest way to find cover that matches your fleet size, vehicle types, and usage patterns at the best price.
Tell Us About Your Fleet
Provide details of each vehicle, including make, model, registration year, and how it is used (commuting, business, haulage). The size and composition of your fleet determines which insurers can quote.
Choose Your Cover Level
Select from third-party only, third-party fire and theft, or comprehensive cover for each vehicle. You can mix cover levels across your fleet if some vehicles need more protection than others.
Review and Compare Quotes
Check each quote for the overall premium, individual vehicle excesses, and any fleet discounts applied. Pay close attention to cover limits for goods in transit if your vehicles carry stock or equipment.
Buy Online and Start Cover
Most fleet insurers can issue your policy and proof of cover within 24 hours. You receive a certificate of insurance for each vehicle on the fleet.
Who Needs Fleet Insurance?
Any business or household running two or more vehicles can benefit from a fleet policy. The type of fleet determines which specialist cover you need.
By fleet size

Small fleet insurance
covers businesses with 2 to 10 vehicles that want to consolidate policies without meeting large-fleet minimums.

Mini fleet insurance
is designed for the smallest fleets of 2 to 5 vehicles, often with simplified underwriting and faster quotes.

Commercial fleet insurance
covers larger business fleets with tailored terms for companies running 10 or more vehicles.

Family fleet insurance
is the domestic equivalent, covering multiple household vehicles under one policy for families.
By vehicle type

HGV fleet insurance
covers trucks over 3.5 tonnes used for haulage, distribution, and heavy goods transport.

Coach fleet insurance
is built for operators running multiple passenger vehicles on scheduled or private hire routes.

Minibus fleet insurance
covers fleets of 8 to 16-seat vehicles used by schools, care homes, and community transport providers.

Fleet van insurance
is designed for businesses running multiple vans for deliveries, trade work, or mobile services.

Multi car and van insurance
combines cars and vans on one policy for businesses running mixed vehicle types.
By business type

Courier fleet insurance
covers multi-drop delivery operations where vehicles are on the road for most of the working day.

Haulage fleet insurance
is for goods transport businesses moving freight on behalf of third parties under hire and reward terms.

Taxi fleet insurance
covers private hire and hackney carriage operators running multiple licensed vehicles.

Car hire fleet insurance
protects rental companies against damage, theft, and third-party claims from customers driving hire vehicles.
What Vehicles Can A Fleet Policy Cover?
Fleet insurers cover most road-legal vehicle types, and many policies allow you to mix different categories on the same fleet.
Mixed Fleets
You do not need every vehicle to be the same type. A builder with two vans, a car, and a flatbed truck can put all four on one fleet policy, provided the insurer covers all vehicle categories.
Some specialist insurers only cover certain vehicle types, so check that your chosen provider can handle the full range of vehicles you operate.
Agricultural and Construction Vehicles
Tractors, combine harvesters, and off-road construction plant can sometimes be added to a fleet policy, but not all insurers will cover them. If your fleet includes vehicles that spend most of their time off public roads, ask for a specialist quote.
| Vehicle Type | Examples | Typical Fleet Use |
| Cars | Saloons, estates, SUVs | Company cars, sales teams, family fleets |
| Vans | Panel vans, Luton vans, tippers | Trades, deliveries, service calls |
| HGVs | 7.5t to 44t rigid and articulated | Haulage, distribution, construction |
| Minibuses | 9–16 seat vehicles | Schools, care homes, tour operators |
| Coaches | 17+ seat vehicles | Tour operators, shuttle services |
| Specialist | Refrigerated, tow trucks, horse boxes | Cold chain, recovery, equestrian |
What Does Fleet Insurance Cover?
Fleet insurance covers the same core protections as individual motor insurance: third-party liability, accidental damage, fire, and theft, applied across every vehicle on the policy.
Third-Party Liability
Every UK vehicle must have at least third-party liability cover by law. Fleet insurance meets this legal requirement for every vehicle on the policy in a single agreement.
Accidental Damage
Comprehensive fleet cover pays to repair or replace your own vehicles if they are damaged in an accident, regardless of who was at fault. For fleets covering high-value or business-critical vehicles, this is the most important element of the policy.
Fire and Theft
Third-party fire and theft cover protects your vehicles against fire damage, theft, and attempted theft. It does not cover accidental damage caused by your own drivers.
Windscreen and Glass
Comprehensive fleet policies usually include windscreen repair and replacement as standard. Claims for windscreen damage typically do not affect your no-claims discount, making this a useful element of comprehensive cover for fleets that clock up high mileage.
Employer and Public Liability
Businesses that employ drivers need employers’ liability insurance to cover workplace injuries. Many fleet operators also carry public liability insurance to protect against third-party property damage or injury caused by their operations.
What Levels Of Cover Are Available?
Fleet policies offer the same three cover levels as individual motor insurance, and you can mix different levels across your fleet if some vehicles need more protection than others.
| Cover Level | What It Covers | Best For |
| Third-Party Only (TPO) | Damage to other vehicles, property, and injury to others | Older, low-value vehicles |
| Third-Party, Fire & Theft (TPFT) | TPO + fire and theft of your own vehicles | Mid-value vehicles stored securely |
| Comprehensive | TPFT + accidental damage to your own vehicles | High-value or business-critical vehicles |
Mixing Cover Levels
Most fleet insurers let you assign different cover levels to individual vehicles. A business might choose comprehensive cover for new delivery vans and third-party only for an older pool car.
Mixing cover levels gives you the flexibility to protect high-value vehicles without overpaying for cover on vehicles worth less than the annual premium increase.
What Add-Ons Can You Include?
Fleet insurance policies offer a range of optional add-ons that extend your cover beyond the standard motor insurance protections.
Goods in Transit
If your vehicles carry stock, tools, or customer goods, goods in transit cover protects the contents against damage, theft, or loss during transport. Cover limits typically range from £5,000 to £50,000 per load, depending on what you carry.
Hire and Reward
Hire and reward cover is required for any vehicle that carries passengers or goods for a fee. Courier services, taxi fleets, and delivery operations all need this add-on to trade legally.
Breakdown and Recovery
Fleet breakdown cover sends a recovery vehicle to any of your fleet vehicles that break down, wherever they are in the UK. For businesses that depend on every vehicle running, this keeps downtime to a minimum.
Courtesy Vehicles
Courtesy vehicle cover provides a temporary replacement while one of your fleet vehicles is being repaired. A day without a vehicle often means lost revenue, making this one of the most cost-effective add-ons for working fleets.
Trailer Cover
If your vehicles tow trailers, flatbeds, or plant equipment, trailer cover extends your policy to include damage to the trailer itself. Standard fleet policies only cover the towing vehicle.
Legal Expenses
Legal expenses cover pays for solicitor and court costs if you need to pursue or defend a claim related to a fleet accident. Most policies offer £100,000 of legal cover as standard or as an affordable add-on.
Without this add-on, the contents of your vehicle are not covered under a standard motor insurance policy. Delivery companies, tradespeople carrying tools, and businesses transporting customer goods should treat this as a priority.
How Much Does Fleet Insurance Cost?
Fleet insurance premiums vary widely depending on fleet size, vehicle types, driver profiles, and claims history, but most small fleets of 3–5 vehicles pay between £1,500 and £5,000 per year.
| Fleet Profile | Vehicles | Annual Premium | Per-Vehicle Saving |
| Family fleet (3 cars) | 3 | £1,200–£2,000 | 10–15% |
| Tradesman (2 vans + 1 car) | 3 | £1,500–£3,000 | 15–20% |
| Courier fleet (5 vans) | 5 | £3,000–£6,000 | 15–25% |
| Haulage fleet (10 HGVs) | 10 | £8,000–£15,000 | 20–30% |
| Large commercial (50+ vehicles) | 50+ | £25,000+ | 25–40% |
What Affects the Cost?
The biggest pricing factors are fleet size, vehicle value, driver age and claims history, and the types of journeys your vehicles make. According to the Association of British Insurers, motor insurance premiums rose by an average of 25% in 2023, making fleet discounts more valuable than ever.
Fleets with younger drivers, high-mileage vehicles, or a history of claims will pay more. Conversely, a clean claims record and experienced drivers can reduce your fleet premium by 20–30%.
Individual vs Fleet Pricing
Fleet insurance is almost always cheaper per vehicle than buying separate individual policies. The savings come from administrative efficiencies, bulk buying power, and a single renewal process.
The discount typically grows as the fleet gets larger. A 3-vehicle fleet might save 10–15%, while a 50-vehicle fleet could save 25–40% per vehicle.
A plumbing company runs three vans, each insured individually at £1,800 per year. That is £5,400 in total premiums, with three separate renewal dates and three sets of paperwork.
Switching to a fleet policy at £4,200 per year saves £1,200 (22%) and consolidates admin into a single renewal. The savings increase further if the company adds a fourth van.
How To Save Money On Fleet Insurance
The single most effective way to reduce fleet insurance costs is to improve your claims record, but there are several practical steps you can take at each renewal.
Invest in Fleet Management
Telematics (black box tracking) monitors driving behaviour across your fleet and rewards safe driving with lower premiums. A formal fleet management programme that tracks mileage, servicing, and driver performance gives insurers confidence that your fleet is well run.
Increase Voluntary Excesses
Raising your voluntary excess from £250 to £500 per vehicle can reduce your premium by 5–10%. Only do this if your business can absorb the extra cost when a claim arises.
Review Your Fleet Annually
Remove vehicles you no longer use and update mileage estimates at each renewal. Insurers price based on declared usage, and over-estimating mileage costs you money.
Improve Vehicle Security
Fitting trackers, immobilisers, and dash cams to every vehicle reduces theft and fraud risk. The Health and Safety Executive also recommends regular vehicle maintenance checks to reduce accident risk for commercial fleets.
Train Your Drivers
Driver training programmes reduce accident frequency and demonstrate to insurers that you take risk management seriously. Some insurers offer premium discounts of 5–10% for fleets with accredited driver training in place.
Pay Annually
Monthly payment plans include interest charges that typically add 10–20% to the total annual cost. Paying upfront avoids this premium if your cash flow allows.
Check each vehicle's value too. If a van has depreciated below £2,000, switching it from comprehensive to third-party only could cut that vehicle's premium by 20–30%.
What Are Your Driver Policy Options?
Fleet insurance offers two main driver structures: named drivers, where each driver is listed on the policy, and any-driver cover, where anyone with a valid licence can drive any vehicle on the fleet.
Named-Driver Policies
Each driver is assessed individually, and the premium reflects their age, experience, and claims history. Named-driver policies are cheaper because the insurer knows exactly who is behind the wheel.
Any-Driver Policies
Any-driver policies cover anyone who drives a fleet vehicle, provided they hold a valid UK licence and meet any minimum age requirements set by the insurer. This suits businesses with casual workers, seasonal staff, or shared vehicles.
How Many Vehicles Do You Need?
Most insurers require at least two vehicles for a fleet policy, although the best discounts usually start at three. Some specialist providers accept mixed fleets of cars and vans from just two vehicles.
The trade-off is admin. Every time you hire or lose a driver, you need to update the policy and the premium may change.
The premium is higher because the insurer cannot assess individual driver risk. However, the flexibility can be worth the extra cost for businesses where driver rotas change frequently.

Frequently Asked Questions
Most insurers require a minimum of two vehicles, although some specialist providers set the threshold at three. The best per-vehicle savings typically start at five or more.
Yes, most fleet insurers let you add or remove vehicles at any time. The premium is adjusted pro-rata, so you only pay for the cover you use.
No, fleet policies can cover a mix of cars, vans, HGVs, minibuses, and specialist vehicles on the same policy.
The driver reports the incident to your fleet manager, who notifies the insurer. The insurer handles the claim, arranges repairs, and provides a courtesy vehicle if your policy includes that add-on.
Yes, but drivers under 25 typically increase the premium. Some insurers offer telematics options that monitor young driver behaviour and reward safe driving with lower costs.
It depends on the policy. Business-only cover is cheaper but restricts vehicles to work use, while social, domestic, and pleasure (SDP) cover allows personal use outside working hours.
In most cases, yes. Fleet insurance is typically 10–30% cheaper per vehicle than buying separate policies, and the discount grows as the fleet gets larger.
Hired vehicles are usually covered by the hire company's insurance. If you hire vehicles long-term or on a contract hire basis, check whether their cover meets your needs before buying additional fleet cover.
Yes, fleet policies can cover vehicles registered to different individuals or companies, provided they all operate as part of the same fleet.
It includes driver training, vehicle maintenance schedules, telematics monitoring, and incident reporting procedures. Insurers reward well-managed fleets with lower premiums.
Comprehensive fleet policies usually include windscreen repair and replacement as standard. Third-party only and third-party fire and theft policies do not.
Start comparing quotes 3–4 weeks before your renewal date. This gives you time to update driver and vehicle details and avoid last-minute gaps in cover.
Yes, most fleet insurers recognise no-claims history from individual policies when you switch to a fleet. A clean claims record across your fleet is one of the biggest factors in reducing your premium.
Fleet insurance covers vehicles used for business purposes and can include vans, HGVs, and specialist vehicles. Multi-car insurance covers two or more cars at the same household address and is designed for personal or family use.