Multi Car & Van Insurance
Multi Car & Van Insurance Quotes
Cover your cars and vans under one fleet insurance policy.

Partnered with Quotezone
We’re partnered with Quotezone. As an Introducer Appointed Representative of Seopa Ltd (FCA FRN: 313860), we receive a commission if you purchase insurance products via SimplyQuote.co.uk.
We do not provide advice or make recommendations. Your choice of provider is entirely your own.




Compare multi car & van insurance policies from leading insurers, including;
What Is Multi Car And Van Insurance?
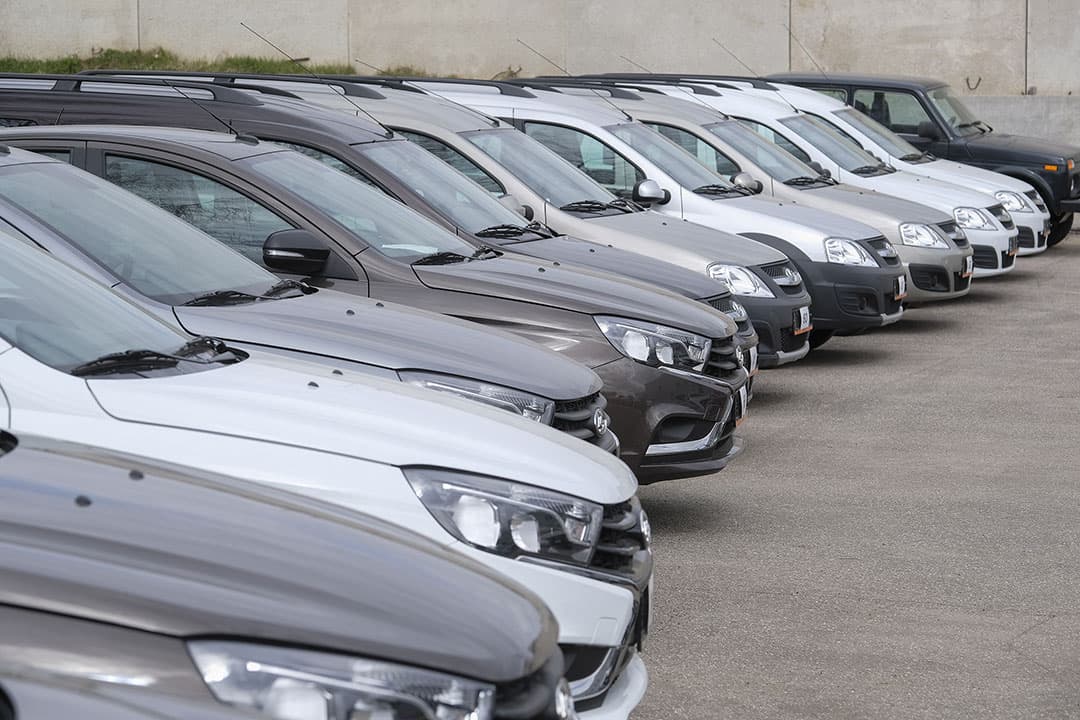
Multi car and van insurance is a single policy that covers two or more vehicles under one plan, combining cars and vans on the same renewal date with the same insurer.
It works like a fleet insurance policy but is designed for smaller groups of vehicles, typically two to four. Bundling your vehicles together often qualifies for a multi-vehicle discount.
If you only have cars, a dedicated multi-car policy may suit you better. Multi car and van insurance is built for households or businesses that run a mix of both.
How To Compare Multi Car And Van Insurance Quotes
Comparing multi car and van insurance quotes takes a few minutes and helps you find the right balance between cover and cost for every vehicle.
Choose cover levels.
You can set different cover levels for each vehicle. A newer van used for work might need comprehensive cover, while an older car used for commuting could run on third-party fire and theft.
Review your quotes side by side.
Check each policy's excess, exclusions, and add-ons before picking the cheapest option. The lowest headline price does not always mean the best value.
Buy online.
Once you have chosen, complete your application and receive your documents by email. Cover can start the same day.
What Does Multi Car And Van Insurance Cover?
A multi car and van policy covers the same risks as individual motor insurance, with the added convenience of managing everything under one plan.
Third-party liability
Every vehicle on UK roads must be insured for at least third-party liability under the Road Traffic Act. This covers damage or injury you cause to other people and their property.
Fire and theft
Third-party fire and theft adds protection if your vehicle is stolen or damaged by fire. This is a common choice for older vans that are still in regular use.
Van theft is a particular risk for businesses that carry tools or stock overnight. Adding fire and theft cover to every van on a multi-vehicle policy is usually cheaper than buying separate policies.
Comprehensive cover
Comprehensive cover includes everything above, plus accidental damage to your own vehicle. Most insurers also include windscreen repair, personal belongings, and a courtesy vehicle.
Goods-in-transit cover
If your vans carry stock, tools, or customer goods, you can add goods-in-transit cover as an extra. Businesses that deliver for third parties may also need hire and reward insurance on top of their standard policy.
Breakdown assistance
Many multi-vehicle policies offer breakdown cover as an add-on for every vehicle on the plan. Buying it as part of your policy is usually cheaper than arranging separate breakdown for each vehicle.
What Levels Of Cover Are Available?
Every vehicle on a multi car and van policy can sit at its own level of cover, so you can match each one to what it is worth and how it is used.
| Cover Level | Own Vehicle Damage | Fire & Theft | Third-Party Liability | Typical Use |
| Third-Party Only | No | No | Yes | Older vehicles, low value |
| Third-Party Fire & Theft | No | Yes | Yes | Mid-value cars and vans |
| Comprehensive | Yes | Yes | Yes | Newer or high-value vehicles |
Compare Multi Car And Van Insurance
Compare multi car and van insurance quotes from UK insurers in minutes.
What Is Not Covered By Multi Car And Van Insurance?
Multi car and van insurance covers most everyday risks, but every policy has exclusions you need to check before you buy.
Vehicles not listed on the policy
Only the vehicles named on your policy are covered. If you buy a new car or van, you need to add it to your policy before driving it.
Incorrect use class
A vehicle insured for social use only is not covered if you use it for business deliveries. Courier drivers and anyone carrying goods for hire need the correct commercial use class declared on their policy.
Driving without a valid licence
Any driver operating a vehicle on your policy must hold a valid UK driving licence for that vehicle class. Unlicensed drivers are excluded from cover.
Wear and tear
Gradual deterioration, mechanical breakdown, and routine maintenance are not covered. Insurance only responds to sudden and accidental events.
Uninsured vehicles left on the road
Under continuous insurance enforcement, any vehicle registered in your name must be insured or declared off the road with a SORN. Failing to do either can result in a fixed penalty, wheel clamping, or your vehicle being seized.
How Much Does Multi Car And Van Insurance Cost?
Multi car and van insurance typically costs 10-20% less than insuring each vehicle separately, with the exact saving depending on how many vehicles you cover and who drives them.
Premiums vary widely based on vehicle types, driver profiles, and cover levels. The Association of British Insurers reports that motor insurance premiums have risen in recent years, making multi-vehicle discounts more valuable than ever.
| Fleet Size | Vehicle Mix | Typical Annual Cost | Estimated Saving vs Separate Policies |
| 2 vehicles | 1 car + 1 van | £800-£1,100 | 10-15% |
| 3 vehicles | 2 vans + 1 car | £1,100-£1,600 | 10-15% |
| 4-5 vehicles | Mixed cars and vans | £1,600-£3,000 | 10-20% |
| 6-10 vehicles | Mixed fleet | £2,500-£5,500+ | 15-25% |
For example, a self-employed plumber with one car and two vans might pay £500 for the car and £550 per van when insured individually, totalling £1,600. A multi-vehicle policy for the same three vehicles could cost around £1,360, saving roughly £240 per year.
For a detailed breakdown of fleet pricing, see our guide on how much fleet insurance costs.
Paying annually rather than monthly saves 8-11% on the total cost, since monthly instalments include interest and admin charges.
What Affects Your Multi Car And Van Insurance Premium?
Several factors determine how much you pay for multi car and van insurance, and understanding them helps you control costs without cutting cover.
Number and type of vehicles
More vehicles on the policy usually means a larger discount, but high-performance cars or heavy goods vehicles attract higher premiums than standard cars and small vans.
Driver ages and experience
Younger drivers and those with less experience push premiums up. Families adding a newly qualified driver to a multi-vehicle policy often find it cheaper than buying a standalone policy for that driver alone.
Vehicle use
Social-only use costs less than business use. Tradesmen using vans for work and cars for commuting need the correct use class on each vehicle, and commercial use always costs more.
Claims and conviction history
A clean record across all drivers on the policy keeps premiums low. One driver with multiple claims can push up the cost for every vehicle on the plan.
Location and overnight storage
Vehicles kept in a locked garage or on a driveway cost less to insure than those parked on the street. Taxi operators and delivery businesses in urban areas typically pay more due to higher theft and accident rates.
What Is The Difference Between Multi Vehicle Insurance And Fleet Insurance?
Multi vehicle insurance and fleet insurance both cover multiple vehicles, but they are designed for different sizes of operation and work in different ways.
Vehicle numbers
Multi vehicle policies typically cover two to four vehicles with named drivers. Fleet insurance is designed for businesses running five or more vehicles and often allows any-driver cover.
Our guide explains how many vehicles you need for fleet insurance and when it becomes the better option.
Named driver vs any driver
Multi vehicle policies list specific drivers for each vehicle. Fleet policies can cover any driver holding the correct licence category, which suits businesses with changing staff.
Named driver policies tend to be cheaper because the insurer knows exactly who is behind the wheel. Any-driver cover trades that saving for operational flexibility.
Which one suits your needs?
A family or sole trader with a few vehicles should start with multi car and van insurance. Businesses that grow beyond four or five vehicles, or that need to swap drivers regularly, should look at fleet van insurance or a mini fleet policy instead.
How To Save Money On Multi Car And Van Insurance
Multi car and van insurance already saves money by bundling vehicles, but there are extra ways to reduce your premium further.
Compare quotes from multiple insurers
Prices for the same group of vehicles can vary by 30% or more between insurers. Comparing quotes side by side is the quickest way to find the best deal.
Pay annually instead of monthly
Monthly instalments add interest and admin fees that increase your total cost by 8-11%. Paying upfront for the full year removes those charges.
Increase your voluntary excess
Raising the voluntary excess on each vehicle lowers the premium. Set it at a level you could comfortably afford if you needed to claim.
Secure overnight parking
Keeping vehicles in a garage or on a driveway reduces the risk of theft and vandalism. Insurers reward secure parking with lower premiums.
Build a no-claims history
Each claim-free year builds your no-claims discount, which can reach 60% or more after five years. Courier fleet operators with clean records across all vehicles see the largest renewal savings.
A higher excess works well on vehicles you rarely claim on. Keep it lower on vans used daily for work, where the chance of minor damage is greater.
Compare Multi Car And Van Insurance
Compare multi car and van insurance quotes from UK insurers in minutes.

Frequently Asked Questions
Most multi-vehicle policies require a minimum of two vehicles. If you have five or more, a dedicated fleet policy may offer better value and more flexibility.
Yes, you can choose comprehensive for one vehicle and third-party fire and theft for another. Each vehicle on the policy can be set to the cover level that matches its value and use.
It can, as long as you declare the correct use class for each vehicle. Social-only cover will not protect you if you use a van for business deliveries.
Most insurers let you add or remove vehicles at any point. There may be an admin fee, and your premium will be adjusted to reflect the change.
In most cases, yes. Bundling vehicles together qualifies for a multi-vehicle discount of 10-20%, depending on the insurer and the number of vehicles.
On a multi-vehicle policy, yes, and each vehicle has its own list of named drivers. Fleet policies offer any-driver cover, which may suit businesses with changing staff.
Most multi-vehicle policies cover standard cars and light commercial vans up to 3.5 tonnes. Larger vehicles like HGVs and trucks usually need a separate HGV fleet policy.
Each vehicle on the policy builds its own no-claims history. A claim on one vehicle does not affect the discount on the others.
Some insurers allow vehicles registered to different household members or business partners on the same policy. Check with the insurer before applying.
Most policies can be arranged online within minutes. Cover typically starts the same day or the next working day.