Campervan Insurance
Compare Campervan Insurance Quotes
Protect your campervan while travelling & enjoying life on the road.
Partnered with Quotezone
We’re partnered with Quotezone. As an Introducer Appointed Representative of Seopa Ltd (FCA FRN: 313860), we receive a commission if you purchase insurance products via SimplyQuote.co.uk.
We do not provide advice or make recommendations. Your choice of provider is entirely your own.




Compare campervan insurance quotes from the UK’s leading insurers including;
What Is Campervan Insurance?
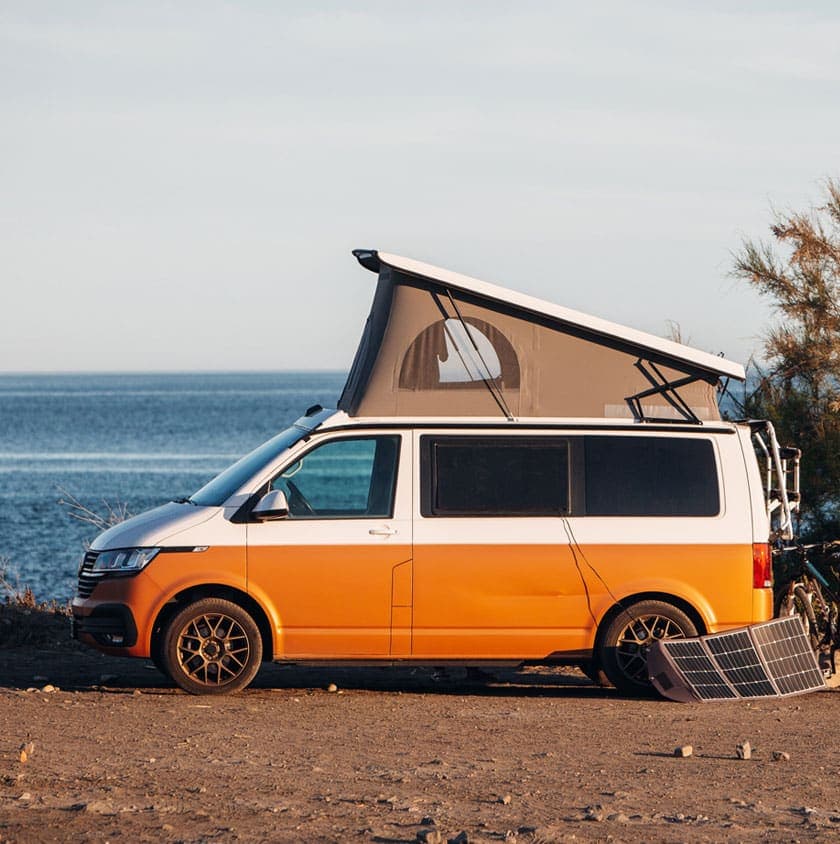
Campervan insurance is a specialist motor policy designed for converted or purpose-built campervans, covering risks that a standard car or van policy would not include.
Unlike a regular van insurance policy, campervan cover accounts for overnight stays, interior modifications, and personal belongings stored inside the vehicle. The DVLA classifies most campervans as motor caravans once they meet specific conversion criteria.
Whether you own a factory-built VW California or a self-converted Sprinter, specialist cover protects both the vehicle and the living space inside it. Policies sit alongside motorhome insurance but are tailored to the smaller, lighter vehicles in this category.
How To Compare Campervan Insurance Quotes
Comparing campervan insurance quotes takes a few minutes online and can save you hundreds of pounds a year.
Enter Your Campervan Details
Provide the registration number, make, model, estimated value, and a list of any modifications. Include conversion details such as pop-top roofs, fitted kitchens, and electrical hookups.
Choose Your Cover Level
Select from third-party only, third-party fire and theft, or comprehensive. Your choice affects both the premium and the protection you receive if something goes wrong.
Review What Each Policy Includes
Check whether personal belongings, European travel, and breakdown assistance are included or available as add-ons. Read the excess amounts and any mileage limits before deciding.
Buy Online and Verify the Provider
Once you have chosen a policy, check the FCA Register to confirm the insurer is authorised. Keep your policy documents where you can access them quickly.
What Does Campervan Insurance Cover?
A standard campervan insurance policy protects you against damage, theft, and third-party claims while your vehicle is on the road or parked up.
Third-Party Liability
Every UK motor policy must include third-party liability as a legal minimum. This pays for damage you cause to other people, their vehicles, or their property.
Accidental Damage
Comprehensive policies cover repair or replacement costs if your campervan is damaged in a collision, reversed into a post, or hit while parked. This extends to the conversion fittings as well as the base vehicle.
Fire and Theft
Fire and theft cover pays out if your campervan is stolen or damaged by fire. This is included in both TPFT and comprehensive policies.
Windscreen Cover
Windscreen replacement or repair is typically included on comprehensive policies without affecting your no-claims bonus. Some policies extend this to side and rear windows.
Personal Belongings
Many specialist policies cover personal items stored inside the campervan, from cooking equipment to clothing. Limits vary by insurer, so check the cap; if you need higher cover, a separate contents insurance policy can fill the gap.
Legal Expenses
Legal expenses cover helps you recover uninsured losses after an accident that was not your fault. This typically includes solicitor fees and court costs up to a fixed limit.
Compare Campervan Insurance
You could save up to £535.17* on your car insurance in minutes
What Types Of Campervan Insurance Can You Get?
There are three main levels of campervan insurance, each offering a different balance of cover and cost.
| Cover Level | What It Includes | Best For |
| Third-Party Only (TPO) | Covers damage to other people and their property only | Older or low-value campervans |
| Third-Party, Fire and Theft (TPFT) | TPO plus cover if your campervan is stolen or damaged by fire | Mid-value vehicles kept in secure locations |
| Comprehensive | TPFT plus accidental damage, windscreen, and personal belongings | Newer campervans or those with expensive conversions |
Comprehensive is the most popular choice for campervans with costly conversion work. The price difference between TPFT and comprehensive is often smaller than owners expect.
What Is Not Covered By Campervan Insurance?
Every campervan policy has exclusions, and knowing what is not covered helps you avoid unexpected gaps when you need to claim.
Full-Time Living
Most policies are designed for leisure use only. If you live in your campervan as a permanent residence, your standard policy is likely to be invalid.
Undeclared Modifications
Any conversion work or aftermarket changes that you have not told your insurer about could void your cover entirely. Always declare pop-top roofs, solar panels, LPG systems, and interior fit-outs.
Business Use Without the Right Cover
Using your campervan for paid work, such as mobile catering or hire-and-reward, requires a commercial or hire-and-reward extension. A standard social, domestic, and pleasure policy will not cover business activities.
Wear and Tear
Gradual deterioration, rust, and mechanical breakdown are maintenance issues, not insurable events. Insurers expect you to keep the vehicle in roadworthy condition.
Theft from an Unlocked Vehicle
If belongings are stolen from a campervan that was left unlocked or with windows open, most insurers will reject the claim. Always secure the vehicle before walking away.
How Does A Campervan Insurance Claim Work?
Filing a campervan insurance claim follows the same process as a standard motor claim, but specialist policies may handle conversion damage differently.
Step-by-Step Process
Contact your insurer as soon as possible after the incident. Provide photos of the damage, a written description of what happened, and a crime reference number if theft or vandalism is involved.
Your insurer will appoint an assessor who understands campervan conversions. Repairs to bespoke interiors may take longer than standard bodywork because specialist fitters are needed.
You reverse into a concrete bollard at a campsite, cracking the rear bumper and denting the tailgate. The repair bill comes to £1,800.
Your comprehensive policy has a £250 voluntary excess. The insurer pays £1,550 directly to the approved repairer, and your campervan is returned within three weeks.
How Much Does Campervan Insurance Cost?
Campervan insurance typically costs between £200 and £600 a year, depending on the vehicle type, its value, and how you use it.
| Campervan Type | Typical Annual Cost | Key Factor |
| Factory-built (e.g. VW California) | £350–£600 | Higher vehicle value |
| Professional conversion | £200–£400 | Quality of conversion work |
| Self-build conversion | £300–£600 | Valuation complexity |
| Classic campervan (e.g. VW T2) | £200–£450 | Agreed value policies |
Younger drivers, high-value conversions, and vehicles kept on the street will sit at the top of these ranges. Owners over 30 with secure parking and limited mileage will pay less.
What Affects Your Premium?
Your age, driving history, postcode, and annual mileage all play a role. The declared value of the conversion work is equally important, because it sets the maximum payout in a total-loss claim.
If you also insure a daily car, ask about multi-vehicle discounts. Some providers offer a saving when you bundle car insurance and campervan cover under the same policy.
How To Save Money On Campervan Insurance
A few practical steps can bring your campervan insurance premium down without reducing the cover you actually need.
Limit Your Annual Mileage
Most campervans cover fewer miles than a daily car. Declaring an accurate, lower mileage signals less risk to insurers and typically lowers your quote.
Park Securely
Keeping your campervan in a locked garage, on a driveway, or in a secure storage compound reduces the theft risk. Insurers reward secure overnight parking with lower premiums.
Increase Your Voluntary Excess
Raising the voluntary excess from £100 to £250 or higher reduces the annual premium. Only choose an excess you could comfortably afford if you needed to claim.
Join an Owners' Club
Some insurers offer discounts to members of recognised campervan or motorhome clubs. Membership also gives you access to group-negotiated rates and specialist advice.
Declare Modifications Accurately
Undeclared modifications can void your policy, but accurately declared ones may not cost as much as you expect. Security upgrades like tracking devices and deadlocks can actually reduce your premium.
SORN During Winter
If you only use your campervan in summer, you can declare a SORN and cancel your insurance for the off-season months. This saves several months of premium, but the vehicle must stay off the public road while uninsured.
If you are heading abroad, compare standalone travel insurance against your insurer's European cover add-on. The cheaper option depends on how many trips you take each year.
Compare Campervan Insurance
You could save up to £535.17* on your car insurance in minutes
What Types Of Campervans Can You Insure?
Specialist insurers cover a wide range of campervans, from mass-produced models to one-off self-builds and imported vehicles.
Factory-Built Campervans
Vehicles like the VW California, Ford Nugget, and Mercedes Marco Polo come with manufacturer-fitted living spaces. These are the simplest to insure because their specifications are standardised.
Professional Conversions
Companies that convert base vehicles such as VW Transporters, Ford Transits, and Mercedes Sprinters produce campervans with documented build specs. Insurers treat these similarly to factory models, especially when the converter is a recognised name.
Self-Build Conversions
If you have converted a van yourself, you will need to provide a detailed list of the work completed, receipts for parts and materials, and photographs. The DVLA vehicle registration process requires your conversion to meet specific standards before it can be reclassified as a motor caravan.
Classic Campervans
Vintage vehicles like the VW T2 Splitscreen or Bedford CF qualify for agreed-value policies that fix the payout amount at the start of the policy. If you own a pre-1980 model, a classic car insurance specialist may also be worth comparing.
Japanese Imports
Imported campervans such as the Mazda Bongo and Toyota HiAce are popular in the UK. Not every insurer covers imports, so use a specialist provider that understands left-hand-drive or grey-import vehicles.
If you are deciding between a campervan and a towed option, compare the costs against caravan insurance to see which suits your travel plans better.

Frequently Asked Questions
Yes, if your campervan is kept off the road and not insured or taxed during winter, you must declare a Statutory Off Road Notification with the DVLA. You can re-tax and insure it when the season starts again.
A standard Category B licence covers campervans weighing up to 3,500 kg, which includes most converted vans and factory-built models. Heavier vehicles such as large coachbuilt motorhomes may need a Category C1 licence.
Most policies cover you wherever you legally park overnight, including wild camping in areas where it is permitted. Check your policy wording for any restrictions on off-road use.
Yes, many specialist insurers cover self-build conversions. You will need to provide build documentation, receipts, and photographs so the insurer can agree a value for the conversion work.
Some policies include European cover as standard for up to 90 days, while others offer it as a paid add-on. Check the territorial limits before you travel.
Yes, provided you declare every modification when you take out or renew the policy. Undeclared changes can void your cover entirely.
Most specialist providers offer breakdown and recovery as an optional extra. This is worth considering for older vehicles or long trips where a standard roadside service may not cover vehicle height or weight.
Many policies include cover for personal items stored in the campervan, usually up to a fixed limit of £1,000 to £3,000. High-value items such as laptops or cameras may need separate cover.
Yes, but not all insurers accept imported vehicles. Specialist providers that cover grey imports or left-hand-drive campervans are your best option.
If you have converted a panel van into a campervan, the DVLA requires you to update the vehicle classification to motor caravan. This involves meeting specific criteria for sleeping, cooking, and seating.
Yes, most policies allow you to add named drivers. Adding an experienced driver with a clean record may not increase your premium by much.
Premiums are often comparable to or slightly higher than standard car insurance. The specialist nature of the cover and the lower annual mileage can offset the higher vehicle value.