Fish and Chip Shop Insurance
Fish & Chip Shop Insurance Quotes
Cover for chippy premises, fryers and stock.
Partnered with Quotezone
We’re partnered with Quotezone. As an Introducer Appointed Representative of Seopa Ltd (FCA FRN: 313860), we receive a commission if you purchase insurance products via SimplyQuote.co.uk.
We do not provide advice or make recommendations. Your choice of provider is entirely your own.




Compare fish & chip shop insurance quotes from leading business premises insurers including;
What Is Fish And Chip Shop Insurance?
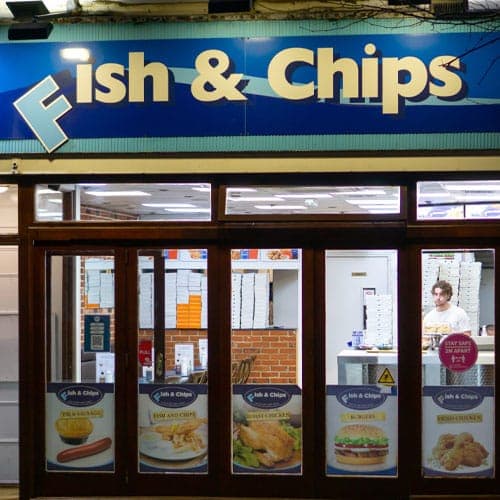
Fish and chip shop insurance is a specialist business policy that protects chip shop owners against property damage, liability claims, equipment failure, and the financial risks of running a food takeaway.
Chippies face hazards that standard commercial property insurance does not cover. Deep-fat fryers, hot oil, high footfall, and food hygiene obligations all create risks that require dedicated protection.
Whether you run a traditional counter-service chippy or a sit-down fish and chip restaurant with a delivery service, the right policy covers your premises, your equipment, your staff, and your customers.
How To Compare Fish And Chip Shop Insurance Quotes
You can compare fish and chip shop insurance quotes online through SimplyQuote in partnership with Quotezone, matching you with FCA-regulated insurers who cover food businesses.
Enter your business details
Provide your postcode, the type of food business you run, your annual turnover, and how many staff you employ.
Select your cover needs
Choose the areas you need to protect, including buildings, contents, liability, and any optional extras such as equipment breakdown or goods in transit.
Review your quotes
Results appear from insurers regulated by the Financial Conduct Authority, each tailored to your setup and risk profile.
Buy your policy online
Once you have chosen a quote, you can apply directly and receive your policy documents by email.
What Does Fish And Chip Shop Insurance Cover?
A fish and chip shop insurance policy typically covers your premises, your equipment, your staff liabilities, and the financial impact of being unable to trade.
Buildings Insurance
If you own your chip shop, buildings insurance covers the cost of repairing or rebuilding the property after fire, flood, storms, or vandalism. Chip shops carry a higher fire risk than most retail premises because of deep-fat fryers and extraction systems.
Contents Insurance
This covers your kitchen equipment, furniture, fridges, freezers, point-of-sale systems, and signage. A commercial deep-fat fryer alone can cost £1,000 to £8,000, so replacing a full kitchen fit-out without cover would be costly.
Employers' Liability
Employers' liability insurance is a legal requirement if you have staff, with a minimum cover level of £5 million. It protects against claims from employees who are injured or become ill because of their work.
Public and Product Liability
Public liability insurance covers claims from customers or visitors who are injured on your premises. Product liability covers claims if someone becomes ill from food you have served.
Business Interruption
If your chip shop cannot trade due to fire, flood, or another insured event, business interruption cover replaces your lost income while repairs are carried out. This is particularly important for chippies that rely on daily cash flow.
Stock Insurance
Covers the cost of replacing food stock, cooking oil, packaging, and other materials if they are damaged, spoiled, or stolen. A sudden fridge or freezer failure can destroy hundreds of pounds of fish and potatoes overnight.
Compare Fish And Chip Shop Insurance
Compare fish and chip shop insurance quotes from UK insurers in minutes.
What Types Of Fish And Chip Shops Can You Insure?
Fish and chip shop insurance can be tailored to suit any type of chippy, from a small counter-service takeaway to a large sit-down restaurant with a delivery arm.
| Business Type | Key Cover Considerations |
| Counter-service takeaway | Contents, PL, product liability, stock, fryer cover |
| Sit-down fish and chip restaurant | Higher PL limits, furniture, alcohol licence (if applicable) |
| Mobile fish and chip van | Commercial vehicle, goods in transit, temporary premises |
| Fish and chip franchise | Multi-site cover, franchisee liability, brand obligations |
| Chippy with delivery service | Delivery driver cover, goods in transit, vehicle insurance |
| Seaside or tourist-location chippy | Higher footfall risk, seasonal business interruption |
If your business also sells other hot food, you may find that a broader takeaway insurance policy is a better fit. Disclose your full menu when requesting a quote so insurers can assess your risk accurately.
What Is Not Covered By Fish And Chip Shop Insurance?
Fish and chip shop insurance does not cover every situation. Exclusions typically apply where equipment is poorly maintained, food hygiene rules are broken, or damage results from gradual wear and tear.
Equipment Neglect
If a deep-fat fryer fails because it has not been serviced, insurers may reject the claim. Most policies require you to maintain kitchen equipment to manufacturer standards.
Food Hygiene Breaches
Claims arising from a failure to follow Food Standards Agency guidelines may be excluded. This includes serving food past its use-by date or failing to store stock at the correct temperature.
Gradual Deterioration
Wear and tear to flooring, extraction hoods, or fixtures is not covered. Insurers expect chip shop owners to maintain their premises to a reasonable standard.
Intentional Damage
Damage caused deliberately by the business owner or staff is excluded. This includes any act intended to trigger an insurance payout.
What Add-Ons Are Available For Fish And Chip Shop Insurance?
Most fish and chip shop policies offer optional extras that let you extend your protection beyond the core cover.
Equipment Breakdown
Covers the cost of repairing or replacing fryers, ranges, refrigeration units, and extraction systems after a sudden mechanical or electrical failure. This is one of the most valuable add-ons for any chippy.
Goods in Transit
If you offer a delivery service, this covers food and supplies while they are being transported. It also protects stock being moved between premises or collected from suppliers.
Money Cover
Covers cash on your premises or in transit to the bank, up to a set limit. Most policies require cash to be stored in a locked safe outside of trading hours.
Legal Expenses
Covers the cost of employment disputes, contract disagreements, and food safety investigations. Chip shops with staff are more likely to face tribunal claims than sole-trader businesses.
Tenants' Improvements
If you rent your premises and have made changes such as installing extraction systems, new counters, or flooring, this covers the cost of repairing or replacing those improvements after an insured event.
How Much Does Fish And Chip Shop Insurance Cost?
Fish and chip shop insurance typically costs between £800 and £3,000 per year, depending on the size of your business, your location, and the level of cover you choose.
| Business Size | Typical Annual Premium |
| Small counter-service chippy (1–2 staff) | £800–£1,500 |
| Medium takeaway (3–5 staff) | £1,500–£2,200 |
| Large sit-down chippy (6–10 staff) | £2,200–£3,000 |
| Multi-site or franchise operator | £3,000–£6,000+ |
Paying annually rather than monthly usually saves 8–11% on the total cost. Monthly instalments are available from most insurers if cash flow is a concern.
A family-run counter-service chippy in a Midlands town with 3 staff, a rebuild value of £200,000, £30,000 in contents, a clean claims history, and a food hygiene rating of 5 might pay between £1,400 and £1,800 per year for buildings, contents, EL, PL, product liability, and business interruption.
What Affects Your Fish And Chip Shop Insurance Premium?
Your premium is based on the level of risk your chip shop presents, including your location, the equipment you use, and your claims history.
Location
Chip shops in high-crime areas or flood-risk zones pay more. Seaside locations may also attract higher premiums due to storm exposure.
Equipment Value
The more expensive your kitchen setup, the higher your contents cover needs to be. A modern commercial kitchen with multiple fryers, a bain-marie, and a walk-in freezer costs more to insure than a basic setup.
Number of Staff
More employees increase your employers' liability exposure. Seasonal staff should also be declared on your policy.
Delivery Service
If you deliver food, insurers factor in the additional risk of drivers on the road. You may need separate commercial vehicle cover depending on your policy.
Claims History
A clean claims record over three to five years results in more competitive quotes. Previous fire damage or food hygiene claims will push your premium higher.
Food Hygiene Rating
A score of 5 (very good) from your local authority signals lower risk to insurers. Scores of 3 or below may increase your premium.
How To Save Money On Fish And Chip Shop Insurance
You can reduce the cost of fish and chip shop insurance by managing your risks, maintaining your equipment, and comparing quotes from specialist insurers.
Service Your Fryers Regularly
Regular maintenance of deep-fat fryers and extraction systems reduces your risk profile and can lower your premium. Follow Health and Safety Executive catering guidance for best practice.
Install Fire Suppression Systems
Automatic fire suppression over fryers and ranges is one of the most effective ways to reduce your premium. Check government fire safety guidance for your legal obligations.
Maintain a High Food Hygiene Rating
A rating of 5 demonstrates strong food safety practices and can result in lower premiums. Poor ratings signal higher product liability risk.
Pay Annually
Paying your premium in a single annual payment rather than monthly instalments typically saves 8–11% on the total cost.
Compare Through a Specialist Service
Using a comparison service like SimplyQuote lets you see quotes from multiple business insurance providers in one place, helping you find the best price for your chip shop.
Compare Fish And Chip Shop Insurance
Compare fish and chip shop insurance quotes from UK insurers in minutes.

Frequently Asked Questions
Employers' liability insurance is a legal requirement if you employ staff, with a minimum cover level of £5 million. Other types of cover are not legally required but are strongly recommended to protect your business, your customers, and your premises.
If you rent, your landlord arranges buildings insurance. You still need contents, liability, business interruption, and stock cover.
Some policies include delivery driver cover, but others require a separate commercial vehicle policy. Check with your insurer whether your delivery service is included.
Most insurers do not require a certificate before quoting, but your food hygiene rating may affect your premium. A rating of 5 signals lower risk to insurers.
Multi-site operators can often arrange a single policy covering all locations. This is usually more cost-effective than separate policies for each shop.
Contents insurance covers your fryers as standard. Equipment breakdown cover, available as an add-on, protects against sudden mechanical or electrical failure that maintenance alone would not prevent.
Fire damage is covered under buildings and contents insurance. However, if the fire resulted from a failure to maintain or service the fryer, insurers may reduce or reject the claim.
Product liability insurance covers claims from customers who become ill from food you have served, though claims arising from food hygiene breaches may be excluded. The same principle applies to restaurant insurance and other food business cover.
A mobile chip van needs commercial vehicle insurance, public liability, and product liability cover at a minimum. Contents cover for your onboard equipment is also recommended.
Through SimplyQuote, you can compare quotes in minutes. Once you choose a policy, documents are typically emailed the same day and cover can start immediately.