
Do You Have to Disclose Car Modifications to Your Insurer?


Yes, you must tell your insurer about every modification that differs from the manufacturer’s original specification. Under the Consumer Insurance (Disclosure and Representations) Act 2012, failing to disclose material facts can lead to claims being rejected or your policy being voided.
The test is not whether a modification is big or small. It is whether a reasonable insurer would factor it into their pricing or underwriting decision, and in practice that means almost every change needs declaring.
Our guide on car insurance costs explains how insurers calculate premiums, including how vehicle specification affects your quote.
Yes, every one of them — anything that differs from the manufacturer’s original specification, including changes you inherited when you bought the car. The definition is wider than most people assume: alloys, tints, a tow bar and a replacement stereo all count. Not declaring is the expensive mistake, because it gives the insurer grounds to cut or refuse a claim that has nothing to do with the modification.
Compare modified car insurance and declare everything properly.
What counts as a modification for insurance purposes?
Anything that differs from how the car left the factory is a modification. This covers performance, cosmetic, mechanical, electrical, and even some safety changes.
Which types of modification must you declare?
| Category | Examples | Typical premium impact |
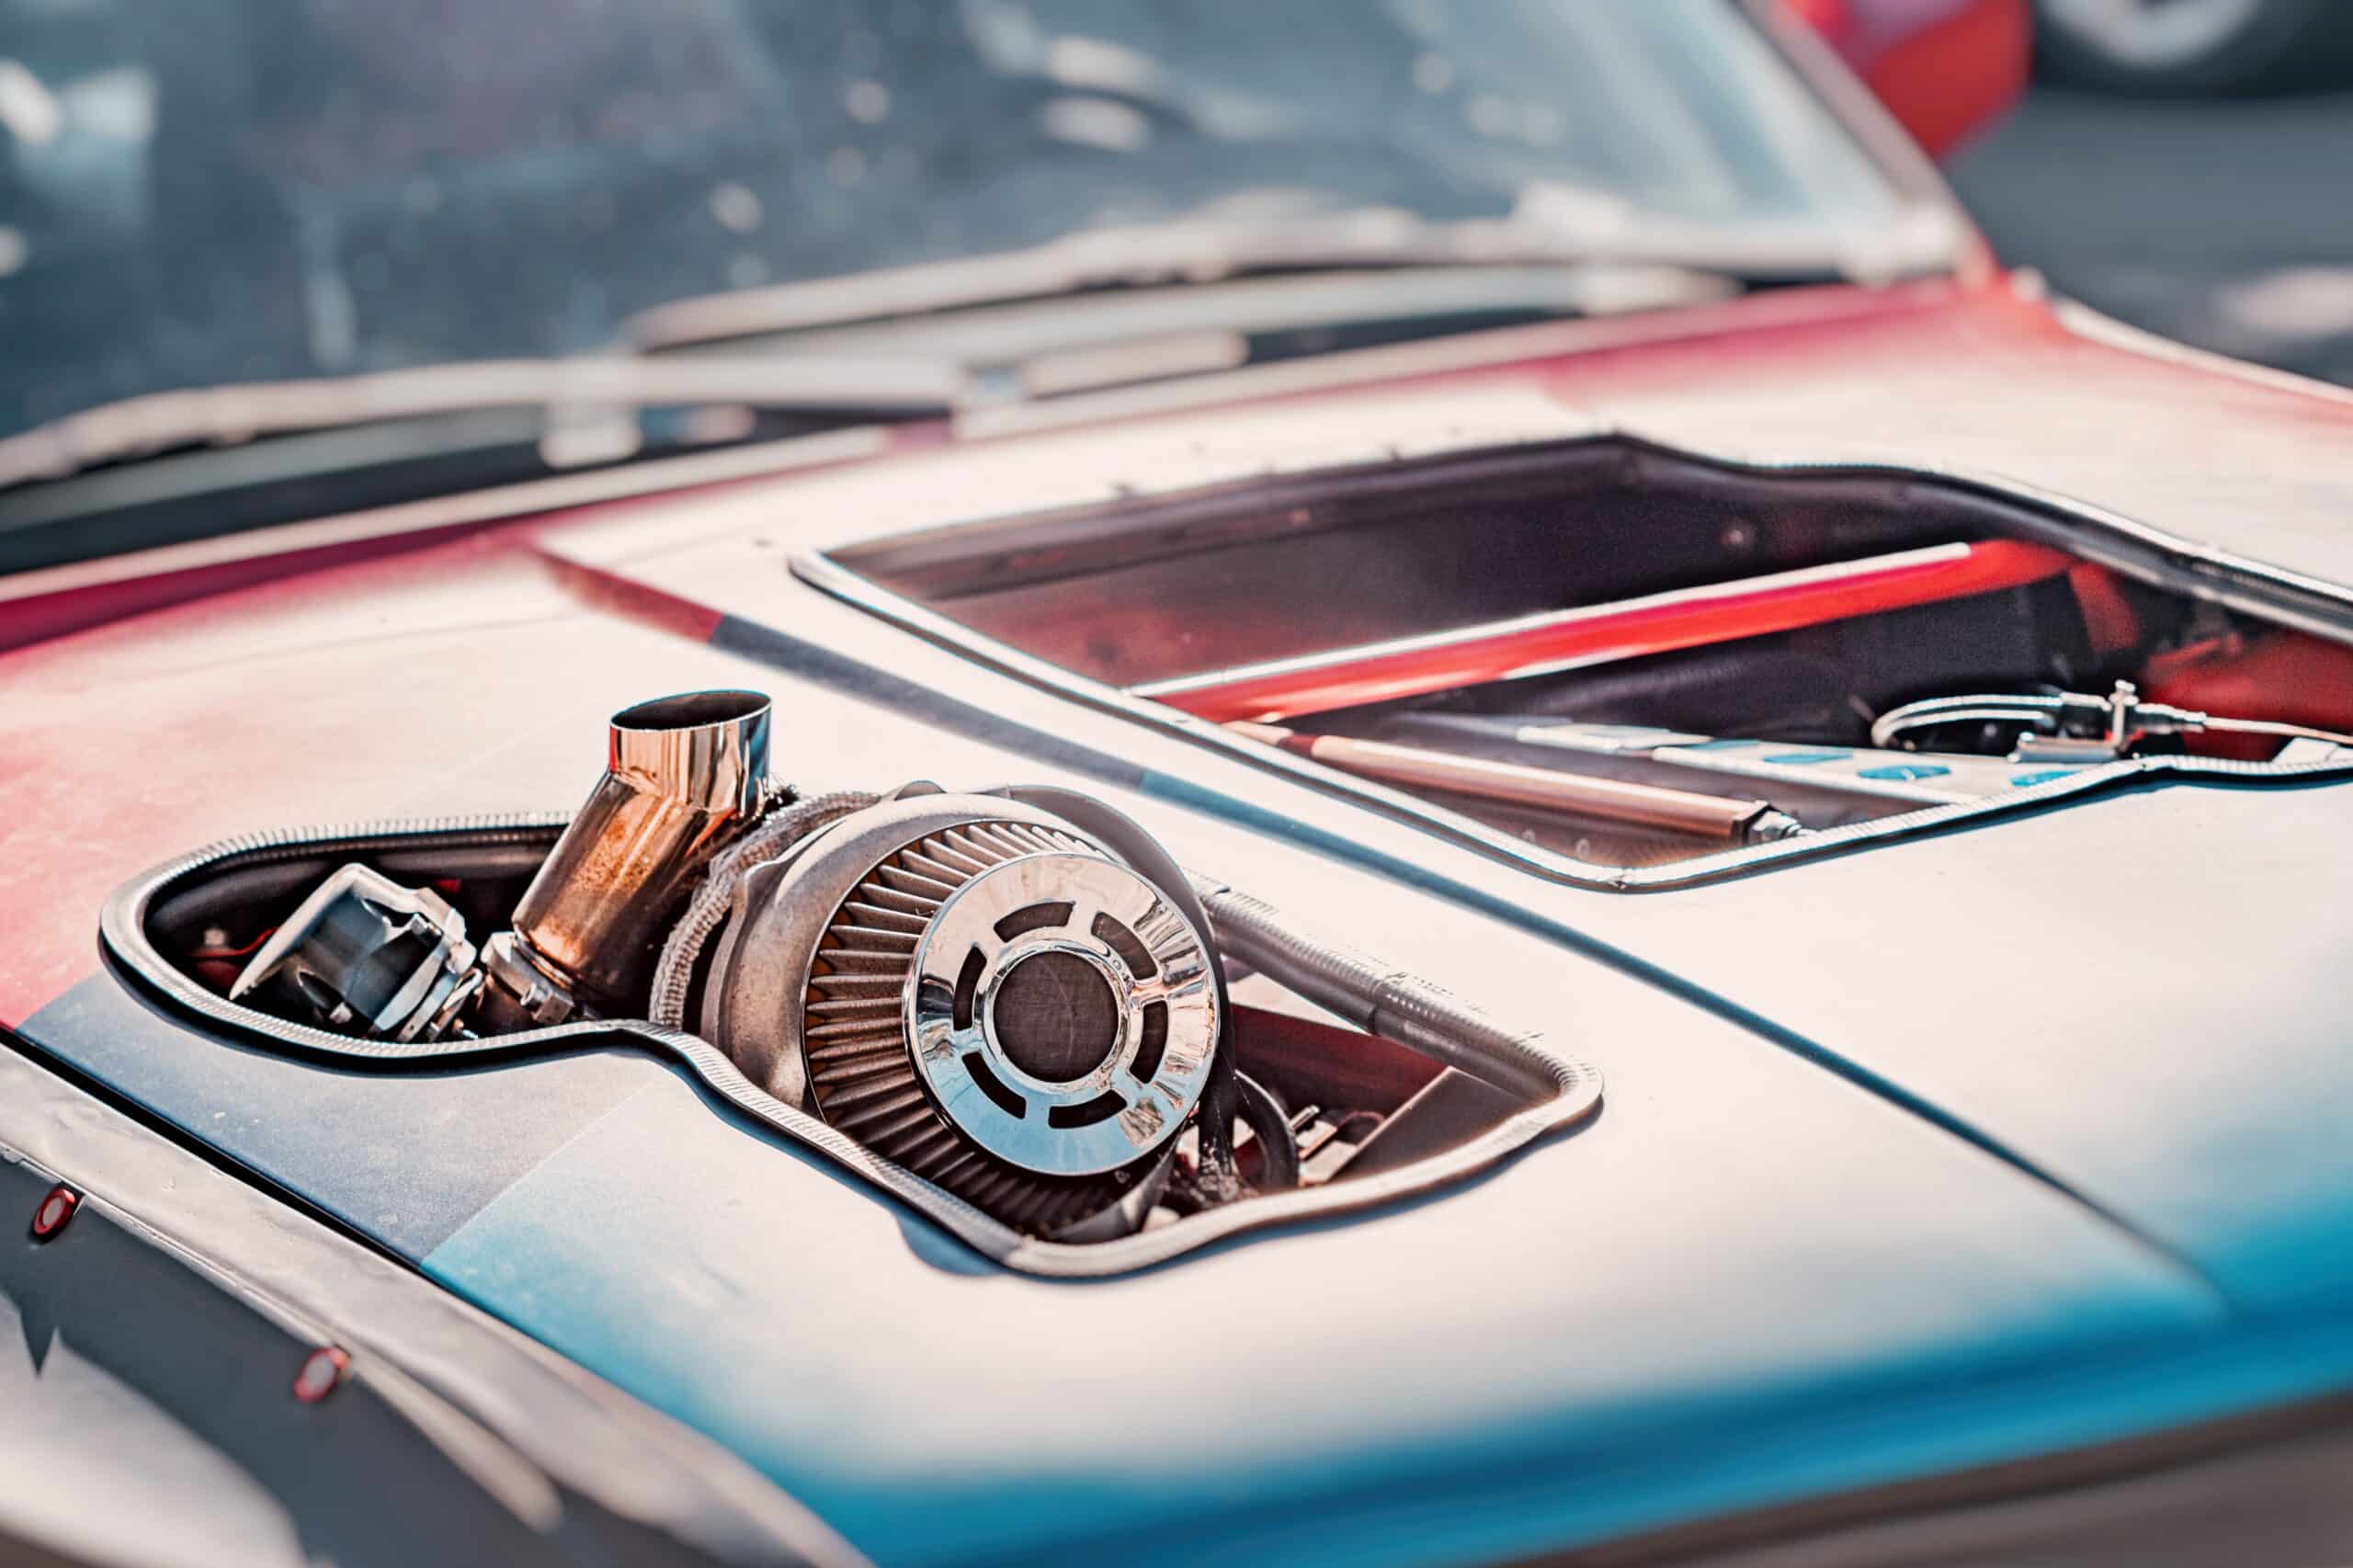
| Performance | ECU remap, turbo, exhaust, intake system | Increase (10-30%+) |
| Suspension | Lowering kit, uprated dampers, performance brakes | Increase (5-15%) |
| Cosmetic | Aftermarket alloys, body kit, vinyl wrap, tinting | Small increase or neutral |
| Electrical | LED headlight conversion, hardwired dashcam, sound system | Neutral to small increase |
| Safety | Roll cage, harness, upgraded brakes | Varies by insurer |
If a previous owner modified the car before you bought it, you are still responsible for declaring those modifications. You must disclose the current state of the vehicle, not just changes you personally made.
When buying a used car, check for any non-standard parts before completing the purchase. Aftermarket exhausts, lowered suspension, and tinted windows are common modifications that previous owners may not mention.
What happens if you do not disclose modifications?
The consequences range from a premium adjustment to your entire policy being voided, depending on whether the non-disclosure was deliberate, careless, or innocent.
How does the 2012 Act handle non-disclosure?
If the non-disclosure was deliberate or reckless, your insurer can void the policy from inception, refuse all claims, and keep your premiums. This is the worst-case outcome.
For careless non-disclosure, the remedy is proportionate. If your insurer would still have offered cover but at a higher premium, they reduce the claim payout proportionally rather than refusing it entirely.
If the insurer would not have offered cover at all, they can refuse the claim but must refund your premiums. This is fairer than the old all-or-nothing approach that existed before the 2012 Act.
Your insurer does not need to prove the modification caused the accident. The misrepresentation itself is the issue, regardless of whether it is connected to the specific claim.
What are the longer-term consequences?
A voided policy creates a cascading problem. Future insurers will ask whether you have ever had a policy voided or cancelled, and answering yes limits your options to specialist providers like convicted driver insurance at higher premiums.
The Motor Insurers’ Bureau may cover third-party costs on your behalf if you are uninsured, but they will then pursue you to recover those costs. These debts can run into tens of thousands of pounds.
Having a voided policy also appears on insurance databases, making it harder and more expensive to get cover for years afterwards.
How should you disclose modifications properly?
Contact your insurer directly, list every modification in detail, and get written confirmation that they have been noted on your policy.
What is the best approach?
The best time to disclose is before you make the modification. Call your insurer, explain what you are planning, and ask how it will affect your premium and cover.
When you contact your insurer, describe each modification specifically: what was changed, when it was done, and the approximate cost. Ask for an updated policy schedule and keep a copy of the written confirmation.
If you have already made changes without declaring them, disclose them immediately. The longer you wait, the harder it becomes to argue the non-disclosure was innocent rather than careless.
Keep receipts and invoices for all modification work. This documentation protects you if there is ever a dispute about what was disclosed, when it was done, and how much it cost.
Can you add modifications during your policy?
Yes, you can modify your car at any point during the policy year, but each change must be disclosed as soon as it is made. Your insurer will adjust your premium mid-term and update your policy schedule.
What about phased builds?
If you are planning multiple modifications over several months, have an upfront conversation with your insurer about the full scope of work. Some insurers are more modification-friendly than others, and switching mid-project is easier than switching after a claim.
Ask your insurer whether they have a maximum modification limit. Some standard providers will accept two or three minor changes but decline to cover vehicles with four or more modifications.
Your disclosure obligation runs throughout the life of the policy. If you fit new wheels in month three and a remap in month seven, both need declaring at the time they are done.
Knowing where you stand before spending money on parts is better than finding out your cover has been cancelled halfway through a project. Our guide on lowering your car insurance premium covers ways to offset the cost of modification-related increases.
Do modifications always increase your premium?
Not always, because some modifications are viewed neutrally or even positively by certain insurers. The impact depends entirely on your insurer’s underwriting criteria.
The ABI explains how motor insurance pricing works and why different insurers respond differently to the same modification.
Which modifications have the least impact?
Dashcams, parking sensors, and factory-option upgrades typically have a minimal effect on premiums. Some insurers offer discounts for approved security modifications such as Thatcham-rated immobilisers and tracking devices.
Tow bars, roof racks, and disability adaptations are generally treated neutrally by most insurers. However, they still need to be declared because any change to the vehicle specification is considered a modification.
Black box insurance can help offset modification-related increases by rewarding safe driving behaviour with lower premiums. This is particularly useful for younger drivers with modified vehicles.
If your current insurer will not cover your modifications at a reasonable price, specialist modified car insurers often offer better terms. Fully comp cover from a specialist may cost less than third-party only from a mainstream provider for heavily modified vehicles.
Frequently Asked Questions (FAQs)
Yes, even minor changes like non-standard wheels or window tinting must be disclosed. There is no threshold below which a modification becomes too small to declare.
Not necessarily, because under CIDRA 2012 the remedy depends on whether the non-disclosure was deliberate, careless, or innocent. Only deliberate or reckless non-disclosure leads to automatic voiding.
You are responsible for declaring the current state of the vehicle regardless of who made the modifications. If you bought a car with non-standard parts, those must be disclosed.
Non-disclosure is misrepresentation, which is a breach of contract. Deliberate non-disclosure could potentially be prosecuted as fraud under the Fraud Act 2006, but most cases are handled as civil matters.
It depends on the modifications. Many standard insurers cover minor modifications with a premium adjustment, but for multiple or performance modifications, specialist providers often offer better terms.